Saudi Hotel Pipeline Up 13% in Q2 as Giga-Project Awards Plunge
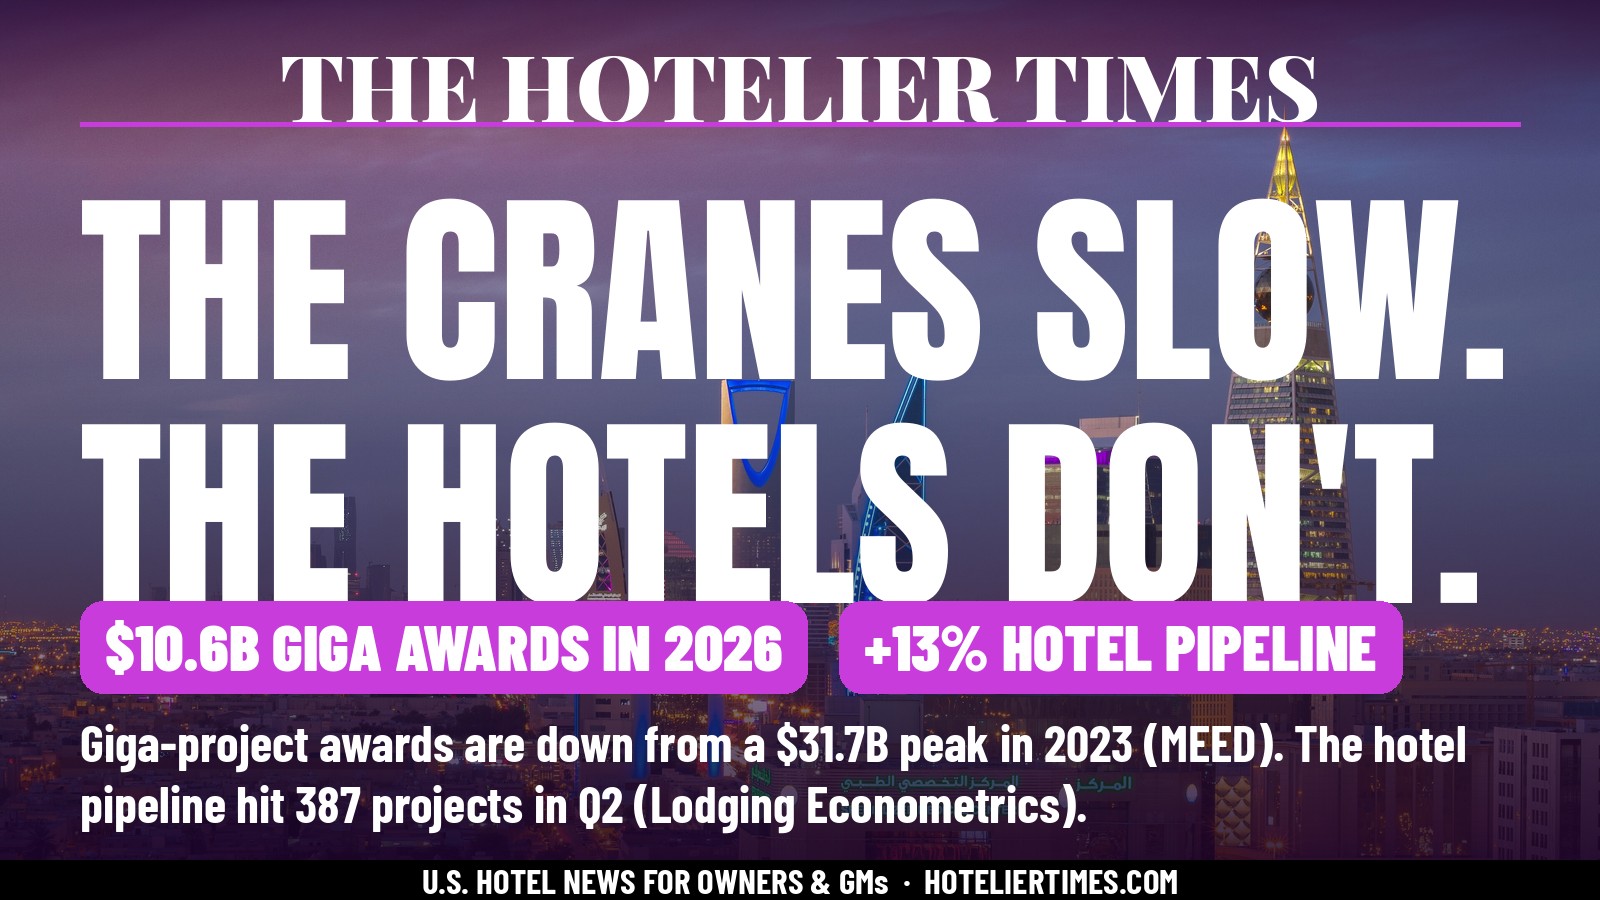
Saudi Arabia has awarded $10.6 billion in giga-project contracts so far in 2026, down from a $31.7 billion peak in 2023, according to MEED as reported by Skift. Yet Lodging Econometrics’ Q2 2026 tally still shows the Saudi hotel pipeline up 13% year over year to 387 projects (105,648 rooms). For U.S. owners and investors, the read-across is about capital priorities, brand fee pipelines and what “Gulf supply” actually means when construction awards and hotel project counts diverge.
Two numbers are circulating together this week. They measure different things. Giga-project contract awards are the construction spend MEED tracks across Neom and other Vision 2030 megaprojects. Hotel project counts are Lodging Econometrics’ pipeline of hotels in planning and construction. One is slowing. The other is still rising. Mixing them into a single “Saudi is canceling hotels” story would be wrong. Separating them is the owner-useful move.
$10.6B So Far in 2026 vs. a $31.7B Peak
Per Skift’s Oct. 28 report, citing Edward James, MEED’s head of content and research, on an Oct. 27 Saudi projects market webinar, Saudi Arabia has awarded $10.6 billion in giga-project contracts so far in 2026. Awards peaked at $31.7 billion in 2023, then fell to $26.7 billion in 2024 and $13.6 billion in 2025 (MEED via Skift).
Skift’s account of James’s remarks ties the decline mainly to Neom — including postponement of The Line and Trojena — rather than a broad scrap of the giga program. About $117 billion has been awarded on giga projects to date, roughly 17% of some $700 billion awarded across the kingdom over the past decade, MEED estimates via Skift. James said the giga-award decline “is not the overriding reason for a drop in project awards in the kingdom.”
This year’s giga awards have gone mostly to Qiddiya and Diriyah, with lesser amounts to Rua Al Madinah and Roshn, per MEED via Skift. MEED expects the next wave to come from projects tied to King Salman International Airport, Expo 2030 and 2034 World Cup stadium work starting around 2027. Overall Saudi contract awards were about $76 billion through October 2026 versus $102 billion last year (MEED via Skift), with Tabuk — home to Neom — hit hardest and Riyadh still taking the bulk of spending.
Hotel Pipeline: +13% to 387 Projects in Q2
Lodging Econometrics’ Q2 2026 Middle East Construction Pipeline puts Saudi Arabia first in the region with 387 projects and 105,648 rooms, up 13% by projects and 15% by rooms year over year. That is a Q2 figure — say so when you brief partners. The Middle East pipeline overall hit an all-time high of 724 projects / 178,003 rooms in the same LE release, with luxury at a record 207 projects / 45,446 rooms. Riyadh alone had 106 projects / 21,666 rooms.
LE forecasts Middle East openings of 83 hotels / 15,149 rooms in 2026, 91 / 22,875 in 2027 and 102 / 24,284 in 2028. Those are regional forecasts, not Saudi-only delivery guarantees. Drawings and openings are different, just as they are in U.S. markets we track in our Dallas Q3 pipeline scorecard and Texas pipeline coverage.
Luxury-Heavy Pipeline vs. Event Demand
Skift’s analysis of the mismatch — Expo 2030 and World Cup crowds looking more mid-scale while the pipeline stays luxury-skewed — lines up with separate Knight Frank work. Knight Frank’s June 2026 KSA Hospitality & Religious Tourism reporting put more than 105,000 rooms under construction or in advanced planning and said more than half of the future pipeline is luxury/upper-upscale, flagging a mid-scale gap. Do not treat Knight Frank’s room count as the same series as LE’s 105,648; methodologies and dates differ. The directional point for brands and owners is the same: luxury is crowded on paper; mid-scale may be the underserved bet if event calendars hold.
What This Means for U.S. Capital, Brands and Fees
No new Gulf-into-U.S. hotel acquisition showed up in today’s briefing. Do not invent one. The useful read-across for U.S. owners and investors is still real:
- Capital priorities are shifting inside the kingdom. MEED’s award mix favors Riyadh-adjacent projects on event deadlines over some Neom packages. That can redirect sovereign and partner attention; it does not automatically equal a new wave of U.S. hotel bids.
- Brand fee pipelines can keep growing while giga awards shrink. LE’s +13% Saudi project count means management and franchise fee calendars for major flags can still expand even as construction awards fall. Owners watching key money and developer attention should separate those clocks.
- Risk is higher on delivery, not only on demand. Cost inflation, schedule slips and security incidents (Skift reports Houthi attacks on Riyadh’s airport since September 2026, including an Oct. 10 strike that killed 13 people) raise the underwriting bar for anyone taking Saudi development or management risk.
- U.S. competitive sets do not feel Saudi keys directly — but U.S. brand pipelines, Gulf LP appetite and global luxury positioning do. For destination-scale context without equating markets, see our Ciel Dubai Marina coverage and brokerage market trends.
For brokers and capital partners, the distinction also matters when someone asks whether “Saudi money is coming back into U.S. hotels.” A slowdown in Neom-linked awards can free attention inside a sovereign balance sheet; it is not evidence of a closed U.S. bid. Until a named buyer, asset and price show up in primary reporting, treat Gulf redeployment talk as hypothesis. Today’s sourced story is simpler: construction awards are down year to date (MEED via Skift), hotel project counts were still up in Q2 (Lodging Econometrics), and brand/fee calendars can keep moving on the second ledger even when the first one cools.
What This Means for Your Hotel
Full Access Pass
Keep reading
Get the rest of this article for 99¢ with a 24-hour Day Pass, or get the Full Access Pass for $1.99/month for every article.
Comments
No comments yet. Start the conversation.