TKO’s Renovation Pledge: $50K–$60K a Room, and Sonesta Stays on the Table
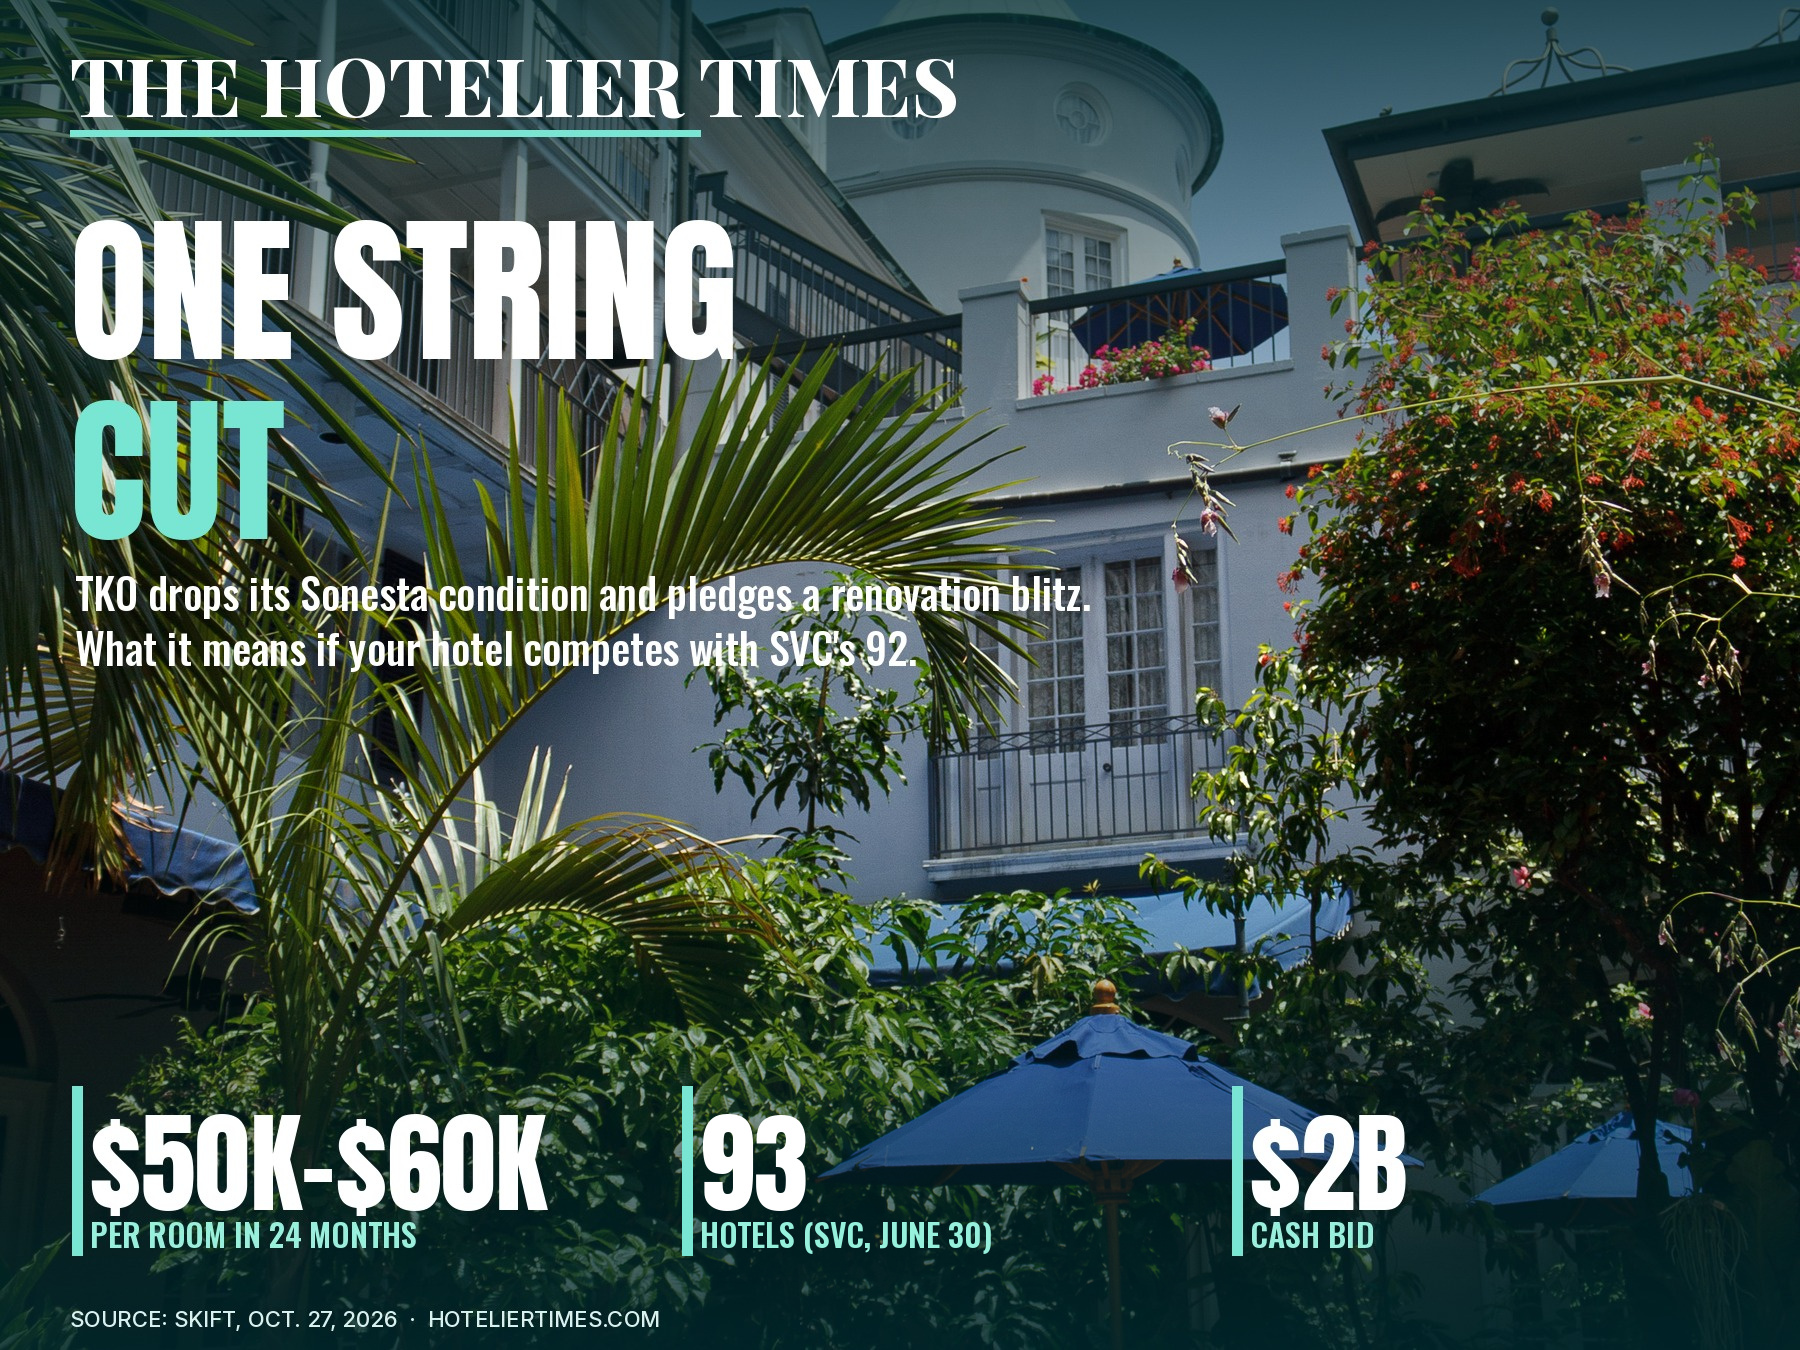
$50,000 to $60,000 a room. That is what TKO says it would spend on Service Properties Trust’s hotels in the first 24 months, according to Skift’s Oct. 27 interview with CEO Jim Koehler — his first public interview since the bid. And as of Oct. 15, TKO’s own release no longer demands that Sonesta’s agreements be ended before closing.
TKO is still offering $2 billion in cash for SVC’s hotel portfolio. What is new is the public renovation pledge, the Oct. 15 change on Sonesta, and a CEO on the record while financing stays undisclosed and SVC’s board has not accepted or rejected the proposal. Watch SVC’s Q3 results after the close on Nov. 4 and its call on Nov. 5.
What Changed on the Sonesta Condition
TKO’s Oct. 7 letter of intent, posted on SVC’s investor site, required Sonesta’s management and franchise agreements to be terminated by closing, with the seller responsible for related costs. That was the hard edge of the original ask. We covered the early price-per-key math in What a $95,000 Key Is Really Worth.
On Oct. 15, TKO’s PR Newswire release changed the public terms. TKO said it had received “no meaningful response” from SVC and that it is “flexible regarding transaction terms, including purchase price, the potential retention of Sonesta as the hotel franchisor.” That is the primary source for the drop. Skift’s Oct. 27 report, citing Koehler, treats the original termination demand as a negotiating position that was dropped on Oct. 15.
Our brand piece, Your Brand Is for Sale, already noted the Oct. 15 flexibility language. The update for this follow-up is clearer still: the termination condition from the Oct. 7 LOI is no longer TKO’s stated closing demand.
The Renovation Pitch, and the Portfolio Count
Skift reports that TKO would spend $50,000 to $60,000 per room in the first 24 months. That figure does not appear in TKO’s Oct. 9 or Oct. 15 releases; attribute it to Skift’s interview reporting. On roughly 21,000 rooms, desk math from Skift’s per-room range implies about $1.05 billion to $1.26 billion of planned capital in two years — a PIP-scale signal if the money is funded and the work is done.
On hotel count, use the dated figures. SVC’s Oct. 9 release said that as of June 30, 2026, it owned 93 hotels with over 21,000 rooms. Skift on Oct. 27 described 92 hotels and nearly 21,000 rooms. On Oct. 15, SVC closed a separate sale of three hotels for $19.0 million under a prior purchase agreement, according to its Oct. 19 Form 8-K — not the TKO deal. Prefer the dated SVC count, and note Skift’s later figure, until SVC publishes a post-sale inventory.
Financing Is Still Undisclosed
The Oct. 7 LOI said there was no financing contingency and that the purchase price would be paid in cash at closing. TKO has still not publicly disclosed how it would fund the full $2 billion. Skift reports Koehler has offered to share his personal financial statement with the trust and that he holds “nine figures” in cash — his wording, as reported by Skift. Skift also quotes him on “stakes in other companies” when describing his broader holdings; we are not repeating unverified portfolio-size figures from that interview. Nine figures is at least $100 million. It is not a disclosed capital stack for a $2 billion closing.
TKO’s Oct. 15 release offers proof of funds and a $50 million escrow deposit once SVC countersigns a nondisclosure agreement. The original LOI contemplated a $15 million deposit on an asset purchase agreement. Neither is a closed equity commitment letter in the public record.
Where SVC Stands
On Oct. 9, SVC confirmed the unsolicited proposal, said it had had no prior contact with TKO, and said its board “will carefully review and consider” the proposal. Skift reports SVC declined to comment ahead of its earnings period. A search of SVC’s October Form 8-K filings for the TKO proposal by name returned no hit; the October 8-K on file addresses the three-hotel sale. No Schedule 13D by TKO on SVC turned up in the same pass.
SVC has scheduled Q3 results for after the Nasdaq close on Wednesday, Nov. 4, and a conference call for Thursday, Nov. 5, at 10:00 a.m. ET. That window is the next likely place for any board comment, process update or continued silence.
What a Renovation Pledge Does to Value per Key
A ~$95,000-a-key bid plus $50,000 to $60,000 of new capital is a claim about future NOI, not a clean read on today’s trading level. Before a broker drops “the SVC bid” into your sale memo, ask:
- Is the price before or after the renovation spend? The Skift-reported $50,000 to $60,000 a room is new capital on top of the purchase price.
- Who funds it, and when? A pledge in an interview is not a closed construction loan.
- What is the hold period? Capex that lifts ADR in year three does not help a seller who needs a close in six months.
Our Oct. 18 analysis already showed why a portfolio average is not your price: SVC’s own exit cohort was trading far below the headline average. The renovation pitch does not erase that averaging problem. Map any SVC hotels in your competitive set now, so you know which of your markets would feel a heavy remodel first if a deal closed.
What It Means for Sonesta-Flagged Owners
Dropping the termination condition is the biggest change for franchisees outside the SVC portfolio. Keeping a large block of Sonesta rooms under a new owner who says it will spend heavily is a different outcome than a forced exit — and still not risk-free. Oct. 15’s language speaks to Sonesta as franchisor; the original LOI covered management and franchise. Those are not the same thing. A new owner can still reflag later. If you fly Sonesta, pull your franchise agreement now: change-of-control, assignment, performance tests and what your fees buy. (We covered Sonesta’s corporate cuts and the Kempinski process in Your Brand Is for Sale.)
What This Means for Your Hotel
Full Access Pass
Keep reading
Get the rest of this article for 99¢ with a 24-hour Day Pass, or get the Full Access Pass for $1.99/month for every article.
Comments
No comments yet. Start the conversation.