Dallas Leads Again: 184 Hotel Projects, a Shrinking National Pipeline, and a 5% 10-Year
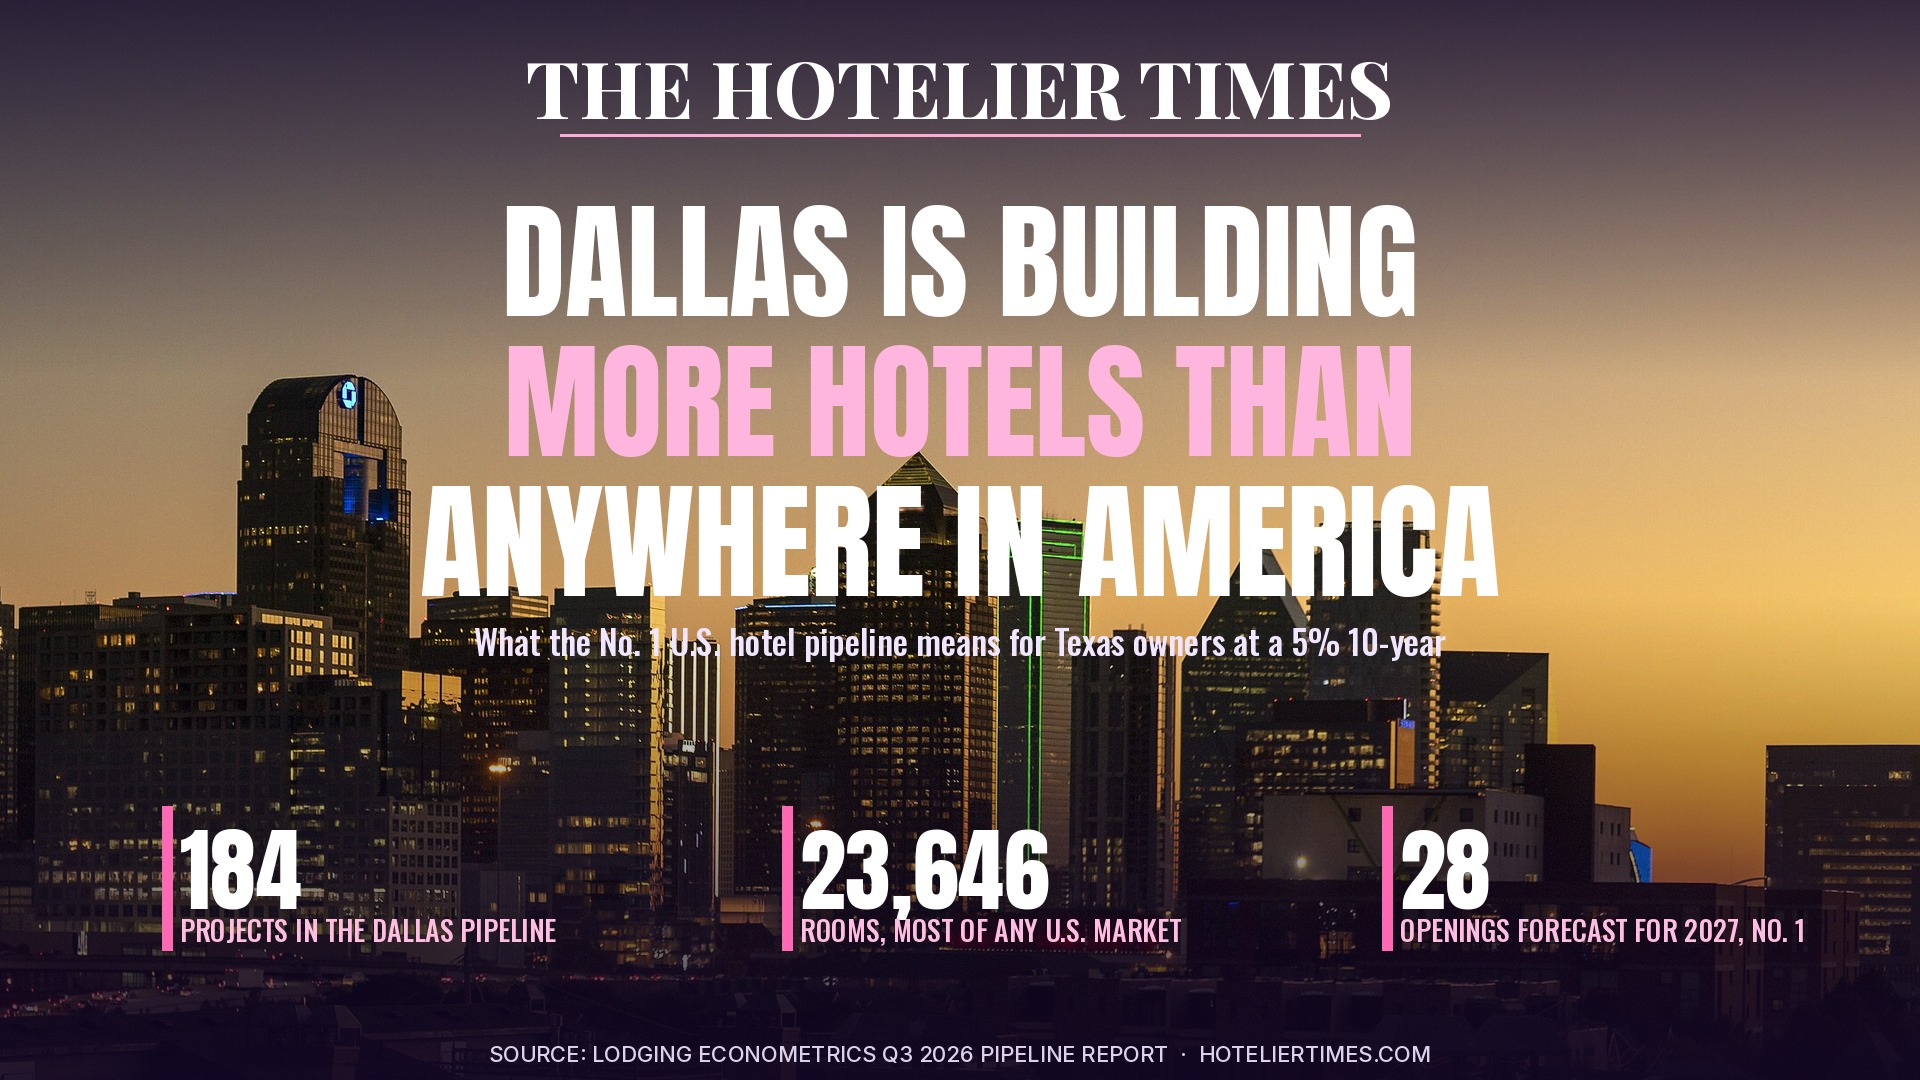
184 projects. 23,646 rooms. Dallas again leads the U.S. hotel construction pipeline by project count — Lodging Econometrics’ Q3 2026 tally — while the national pipeline is actually shrinking. For Texas owners, the question is not who has the most drawings on the wall. It is what that supply does to your RevPAR, and what it costs to build when the 10-year Treasury is sitting near 5%.
Lodging Econometrics’ Q3 2026 market release puts Dallas first among U.S. markets with 184 projects and 23,646 rooms in the total pipeline. Austin is fourth nationally, with 112 projects and 13,169 rooms. Business Travel News, citing LE, says Dallas’s lead by pipeline project count is now its 21st straight quarter. (We covered Frisco, Lockhart and Grapevine project news separately in our Texas pipeline piece; this story is the LE scorecard and what it means for existing owners.)
No. 1 by Project Count — Not on Every Measure
Dallas leads by project count at each pipeline stage LE reports. It does not lead on every rooms measure. Per LE’s markets release, as covered by Hotel Management:
- Under construction: Dallas has the most projects, 36 with 3,764 rooms. New York has fewer projects (28) but more rooms under construction: 6,965.
- Scheduled to start within 12 months: Dallas 72 projects / 8,544 rooms (No. 1 by projects).
- Early planning: Dallas 76 projects / 11,338 rooms (No. 1 by projects).
- 2026 openings forecast (top markets): Phoenix leads; Dallas is second at 18 projects / 2,050 rooms.
- 2027 openings forecast: Dallas is projected to lead with 28 projects / 2,604 rooms.
Say it plainly when you brief your lender or your partners: Dallas is No. 1 by project count. New York still has a bigger under-construction room count. Phoenix is still on track to open more rooms in 2026.
The National Pipeline Is Shrinking. Dallas Is Not the Whole Story.
Nationally, LE counts 5,901 projects and 692,999 rooms in the U.S. hotel construction pipeline at the end of Q3. Hotel projects were down 4.9% year over year, according to Lodging Econometrics, via Hotel Dive. Extended stay accounted for 40% of projects (2,352 projects / 236,219 rooms — about 34% of rooms). Luxury and upper upscale hit record project counts (108 and 375). LE forecasts 598 U.S. hotel openings in 2026, about a 1.2% supply increase.
That national picture is moderate. Dallas’s absolute count is not. Even if some early-planning projects never break ground, the under-construction and next-12-months buckets alone are large relative to other U.S. markets. Austin’s No. 4 ranking adds a second Texas absorption story for owners already competing for group and corporate demand.
Houston and San Antonio: Renovation, Not Ground-Up
Do not confuse renovation tables with new-build pipelines. In LE’s renovation and conversion ranking among top markets, Houston has 31 projects (4,426 rooms) and San Antonio has 30 (2,935 rooms). Those are upgrades and flag swaps, not ground-up counts. Dallas itself has 30 renovation/conversion projects (5,306 rooms). For Houston owners, that lines up with the renovation wave we tracked in our September RevPAR story: capital flowing into older full-service stock while downtown already felt new supply.
Two Projects Already in the Ground
Two named Dallas-area projects show what “under construction” looks like on the ground. Lodging Econometrics does not name individual projects in its public release, so do not read these as LE line items — they are separately reported:
- Americana by Loews, Arlington: a 507-room tower at 1500 Convention Center Drive in the Arlington Entertainment District, with more than 83,000 square feet of meeting space. City and Loews materials described a 2026 start; Groundbreak DFW reported the project under construction as of Oct. 26, with completion expected in 2029.
- Miyako Hybrid Hotel, Plano: a 217-room hotel in The Park at Legacy. D Magazine reported a topping-out ceremony on July 24, 2026, with an opening targeted for fall 2027. It would be Miyako’s first Texas hotel.
What New Supply Means When the 10-Year Is Near 5%
On the morning of Oct. 28, before the Federal Reserve’s decision, the 10-year Treasury yield was about 5.01% (5.0134% in early trading), according to CNBC. Re-check the 10-year (and December hike odds) after the Fed’s 1:00 p.m. CT decision and press conference before publishing — this yield is a pre-decision snapshot. Fixed-rate hotel loans and CMBS takeout pricing still lean on that benchmark. A pipeline full of projects does not mean every project can close construction financing at those levels. Nationally, LE counted only 152 construction starts in Q3 — a reminder that drawings and starts are different.
For existing owners, the rate backdrop and the supply backdrop hit the same P&L. New rooms next door pressure occupancy and rate. A 5% 10-year keeps your own refinance and any expansion loan expensive. We previewed that Fed-day setup in our Oct. 28 Fed decision guide, and the maturity wall in The Refi Clock.
Performance: Use Dated Sources Only
There is no current CoStar or STR metro-wide Dallas RevPAR print in the sources for this piece, so we are not inventing one. Hospitality Ventures Management Group, in its “Market of the Month: Dallas” note, said that through April, Dallas RevPAR declined 1.3% over the trailing 12 months, occupancy fell 0.9% to 64.4%, and ADR rose 0.4%. HVMG attributed pressure to convention-center disruption at the Kay Bailey Hutchison Convention Center and to absorption of new supply. That is operator commentary through April — useful context, not a Q3 STR print.
What This Means for Your Hotel
Full Access Pass
Keep reading
Get the rest of this article for 99¢ with a 24-hour Day Pass, or get the Full Access Pass for $1.99/month for every article.
Comments
No comments yet. Start the conversation.